April 2026 Tax Deadlines: A Comprehensive Guide for Individuals and Small Business Owners
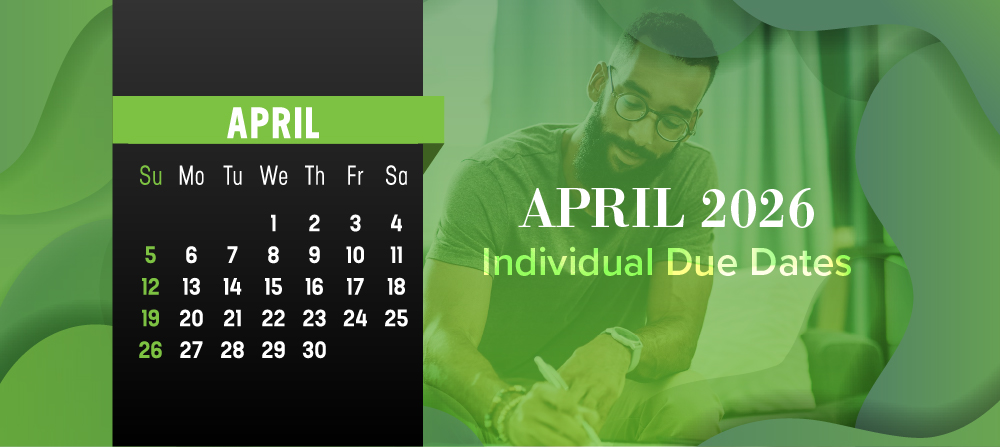
As the calendar turns to April, taxpayers enter the most critical window of the financial year. For individuals, self-employed professionals, and household employers, the coming weeks are packed with essential filing requirements and payment obligations. Missing these dates can lead to unnecessary penalties and interest, so it is vital to stay organized as we approach the mid-month deadline.
April 10: Reporting Tips to Your Employer
For employees who receive tips as part of their compensation, April 10 marks a specific monthly milestone. If you collected more than $20 in tips during the month of March, you are legally required to report that total to your employer. This reporting can be handled via IRS Form 4070 or a detailed personal statement that includes your signature, contact information, Social Security number, and the specific establishment details for the period covered.
Accurate tip reporting ensures that your employer can properly calculate and withhold FICA and income taxes from your standard wages. If your cash wages do not cover the required withholding, the difference will appear in Box 8 of your W-2 at the end of the year, and you will be responsible for that liability when you file your annual return. Staying current with these reports avoids large, unexpected tax bills later on.

April 15: Reporting Foreign Financial Interests (FBAR)
U.S. citizens, residents, and business entities with financial interests in or signature authority over foreign accounts must be mindful of Form FinCEN 114. If the aggregate value of your foreign bank, securities, or other financial accounts exceeded $10,000 at any point during 2025, you are required to file this report electronically with the Treasury Department by April 15, 2026.
While an automatic six-month extension is generally available, the filing process is strictly digital—paper forms are not permitted. If you have assets in overseas accounts, please reach out to our office to ensure your FBAR compliance is handled correctly and submitted on time.
April 15: Individual Income Tax Returns and Extensions
The headline event of the month is the deadline for filing your 2025 federal income tax return (Form 1040 or 1040-SR) and paying any balance due. If you find that you need more time to gather documents or finalize your return, you can request an automatic six-month extension, pushing your filing deadline to October 15, 2026.
However, it is critical to understand the distinction between an extension to file and an extension to pay. An extension only protects you from late-filing penalties. It does not pause the accrual of interest or late-payment penalties on any tax owed. If you anticipate a balance due, paying as much as possible by April 15 is the best strategy to minimize these additional costs. Conversely, if you are owed a refund, filing promptly ensures you aren't providing the government with an interest-free loan longer than necessary.
April 15: Household Employer Compliance
For those who employ household help—such as nannies, housekeepers, or caregivers—April 15 is the deadline for Schedule H. If you paid cash wages of $2,800 or more to a household employee in 2025, you must file this schedule with your individual tax return. Additionally, if you paid $1,000 or more in any calendar quarter of 2024 or 2025, you must report federal unemployment (FUTA) taxes. Managing these “nanny taxes” correctly is a vital part of your overall compliance profile.

April 15: Q1 Estimated Tax Payments for 2026
The U.S. tax system operates on a “pay-as-you-earn” basis. While employees usually meet this through payroll withholding, self-employed individuals and those with significant investment income must make quarterly estimated payments. April 15 is the due date for the first installment of the 2026 tax year.
To avoid underpayment penalties, you generally need to meet one of two “safe harbor” requirements:
- Pay 90% of the tax liability you will owe for the current year.
- Pay 100% of the tax shown on your prior year’s return (or 110% if your adjusted gross income exceeds $150,000).
Consider an example: if your tax for the year is $10,000 but you only prepaid $5,600, you might face a penalty. However, if your prior year’s tax was only $5,000, your $5,600 payment exceeds the 110% threshold ($5,500), protecting you from the penalty even though you still owe the remaining tax balance. Accurate tax planning is essential when you experience large bonuses, property sales, or stock gains.
April 15: Retirement Account Contributions
April 15 is also the final call for 2025 contributions to Traditional and Roth IRAs. Additionally, for the self-employed, this is the last day to establish a Keogh Retirement Account for the 2025 tax year. While Keogh contribution deadlines can be extended to October 15 with a valid filing extension, the setup often requires careful coordination with the April deadline.
Understanding Deadlines, Holidays, and Disasters
IRS rules dictate that if a deadline falls on a Saturday, Sunday, or legal holiday, the due date is moved to the next business day. Furthermore, taxpayers in federally designated disaster areas may be granted additional time to file and pay. You can monitor active designations through FEMA and the IRS disaster relief page.
Navigating these various deadlines can be complex, especially if you have international assets, household employees, or fluctuating self-employment income. To ensure you are meeting your obligations and utilizing all available safe harbors, schedule a consultation with our office today to review your April 2026 tax strategy.
To build a truly effective financial plan, it is helpful to look deeper into the specific mechanics and nuances of these April requirements, starting with the often-overlooked area of tip income reporting. While the monthly reporting threshold is set at a modest twenty dollars, employees in the service and hospitality sectors should maintain a rigorous daily log of all gratuities received. This practice provides a critical layer of protection in the event of an IRS inquiry or audit. It is also important to remember that tip income is not limited to cash; if you receive non-cash tips, such as tickets to sporting events, gift cards, or other items of value, these are technically considered taxable income at their fair market value. While these items are not subject to standard payroll withholding in the same way cash is, they must be accounted for when you calculate your total tax liability for the year.
Regarding the FBAR requirements for those with foreign financial interests, the definition of a foreign account is significantly broader than many taxpayers realize. Beyond standard checking and savings accounts, the Treasury Department requires the reporting of foreign mutual funds, certain types of cash-value life insurance policies, and even digital assets held on exchanges that are based outside of the United States. The signature authority rule is another area where taxpayers frequently run into trouble; for example, if you serve as a power of attorney for an elderly relative living abroad and have your name on their bank accounts, you likely have a filing obligation even if you never use those funds for your own benefit. Given that penalties for failing to file Form FinCEN 114 can be substantial—even in cases where the omission was entirely unintentional—transparency and thoroughness are the best defenses.
When you are weighing the decision to file an extension for your individual return, understanding the mathematical structure of IRS penalties can help you prioritize your payments. The penalty for failing to file a return on time is generally ten times more expensive than the penalty for failing to pay the tax you owe. Specifically, the failure-to-file penalty is five percent of the unpaid tax for each month or part of a month that a return is late, whereas the failure-to-pay penalty is only one-half of one percent per month. By filing your return or a formal extension by the April 15 deadline, you effectively eliminate the more aggressive five percent penalty. If you find yourself in a position where you cannot pay the full balance immediately, the IRS offers several relief options, including short-term payment plans and long-term installment agreements, which can help you manage the debt while stopping the most severe collection actions.
For household employers, the distinction between a worker and an independent contractor is a frequent point of contention during tax season. Under IRS guidelines, if you provide the necessary equipment, dictate the specific hours of work, and maintain the right to control how the tasks are performed, the worker is classified as an employee. This classification means that you are responsible for the administration of payroll taxes via Schedule H. While this requirement adds to your annual filing complexity, it ensures that your household staff members are properly credited for their Social Security and Medicare benefits. Furthermore, by formalizing your household employment and paying the associated taxes, you may become eligible to claim the Child and Dependent Care Credit, which can provide a valuable tax break to offset the costs of domestic help.
Taxpayers with fluctuating or seasonal income, such as independent consultants or small business owners, may find that standard quarterly estimated tax payments do not align well with their cash flow. In these instances, the Annualized Income Installment Method can be a sophisticated tool for managing tax obligations. This method allows you to calculate and pay your taxes based on the income you actually received during specific periods of the year, rather than paying in four equal installments. While this approach requires more detailed bookkeeping and the filing of Form 2210 with your annual return, it is an excellent way to minimize underpayment penalties during the leaner months of your business cycle. Mastery of these safe harbor rules and payment methods ensures that you are not overpaying the government throughout the year at the expense of your own business operations.
Finally, as the April 15 deadline approaches, it is vital to remember that this is the absolute final cutoff for most retirement contributions for the 2025 tax year. While you can extend the deadline for filing your return, you cannot extend the window for making Traditional or Roth IRA contributions. If you are a high-income earner who is technically phased out of direct Roth IRA contributions, you should discuss the possibility of a backdoor Roth conversion strategy with a tax professional. This strategy involves making a non-deductible contribution to a traditional IRA and then promptly converting it to a Roth account, allowing you to benefit from tax-free growth over the long term. Taking the time to evaluate these retirement options before the mid-April deadline can have a profound impact on your wealth accumulation and your eventual tax-free income during retirement.
Want tax & accounting tips and insights?
Sign up for our newsletter.